If your firm has ever developed a new structural approach, tested an unconventional design solution, or worked through real technical uncertainty on a project, you may already be doing R&D work the tax code rewards — most engineering and architecture firms just never claim it.
If you run an engineering or architecture firm anywhere in Frederick County or central Maryland, two federal incentives are worth real attention this year: the R&D tax credit, and a separate, design-specific deduction most firms have never heard of.
Yes, Design Work Can Qualify as R&D
The R&D tax credit isn't limited to laboratories and product manufacturers. To qualify, work needs to rely on engineering, scientific, or technological principles, aim to develop or improve a product, process, or design, and involve genuine experimentation to resolve real technical uncertainty — developing a new structural system, testing an unconventional building approach, or working through a design problem that didn't have an obvious answer from the start.
What doesn't qualify: routine design work using established, standard methods, market research, and quality control after a design is already finalized. The distinction the IRS draws is between genuine technical uncertainty and resolving it through experimentation, versus simply applying well-established design practices to a new project.
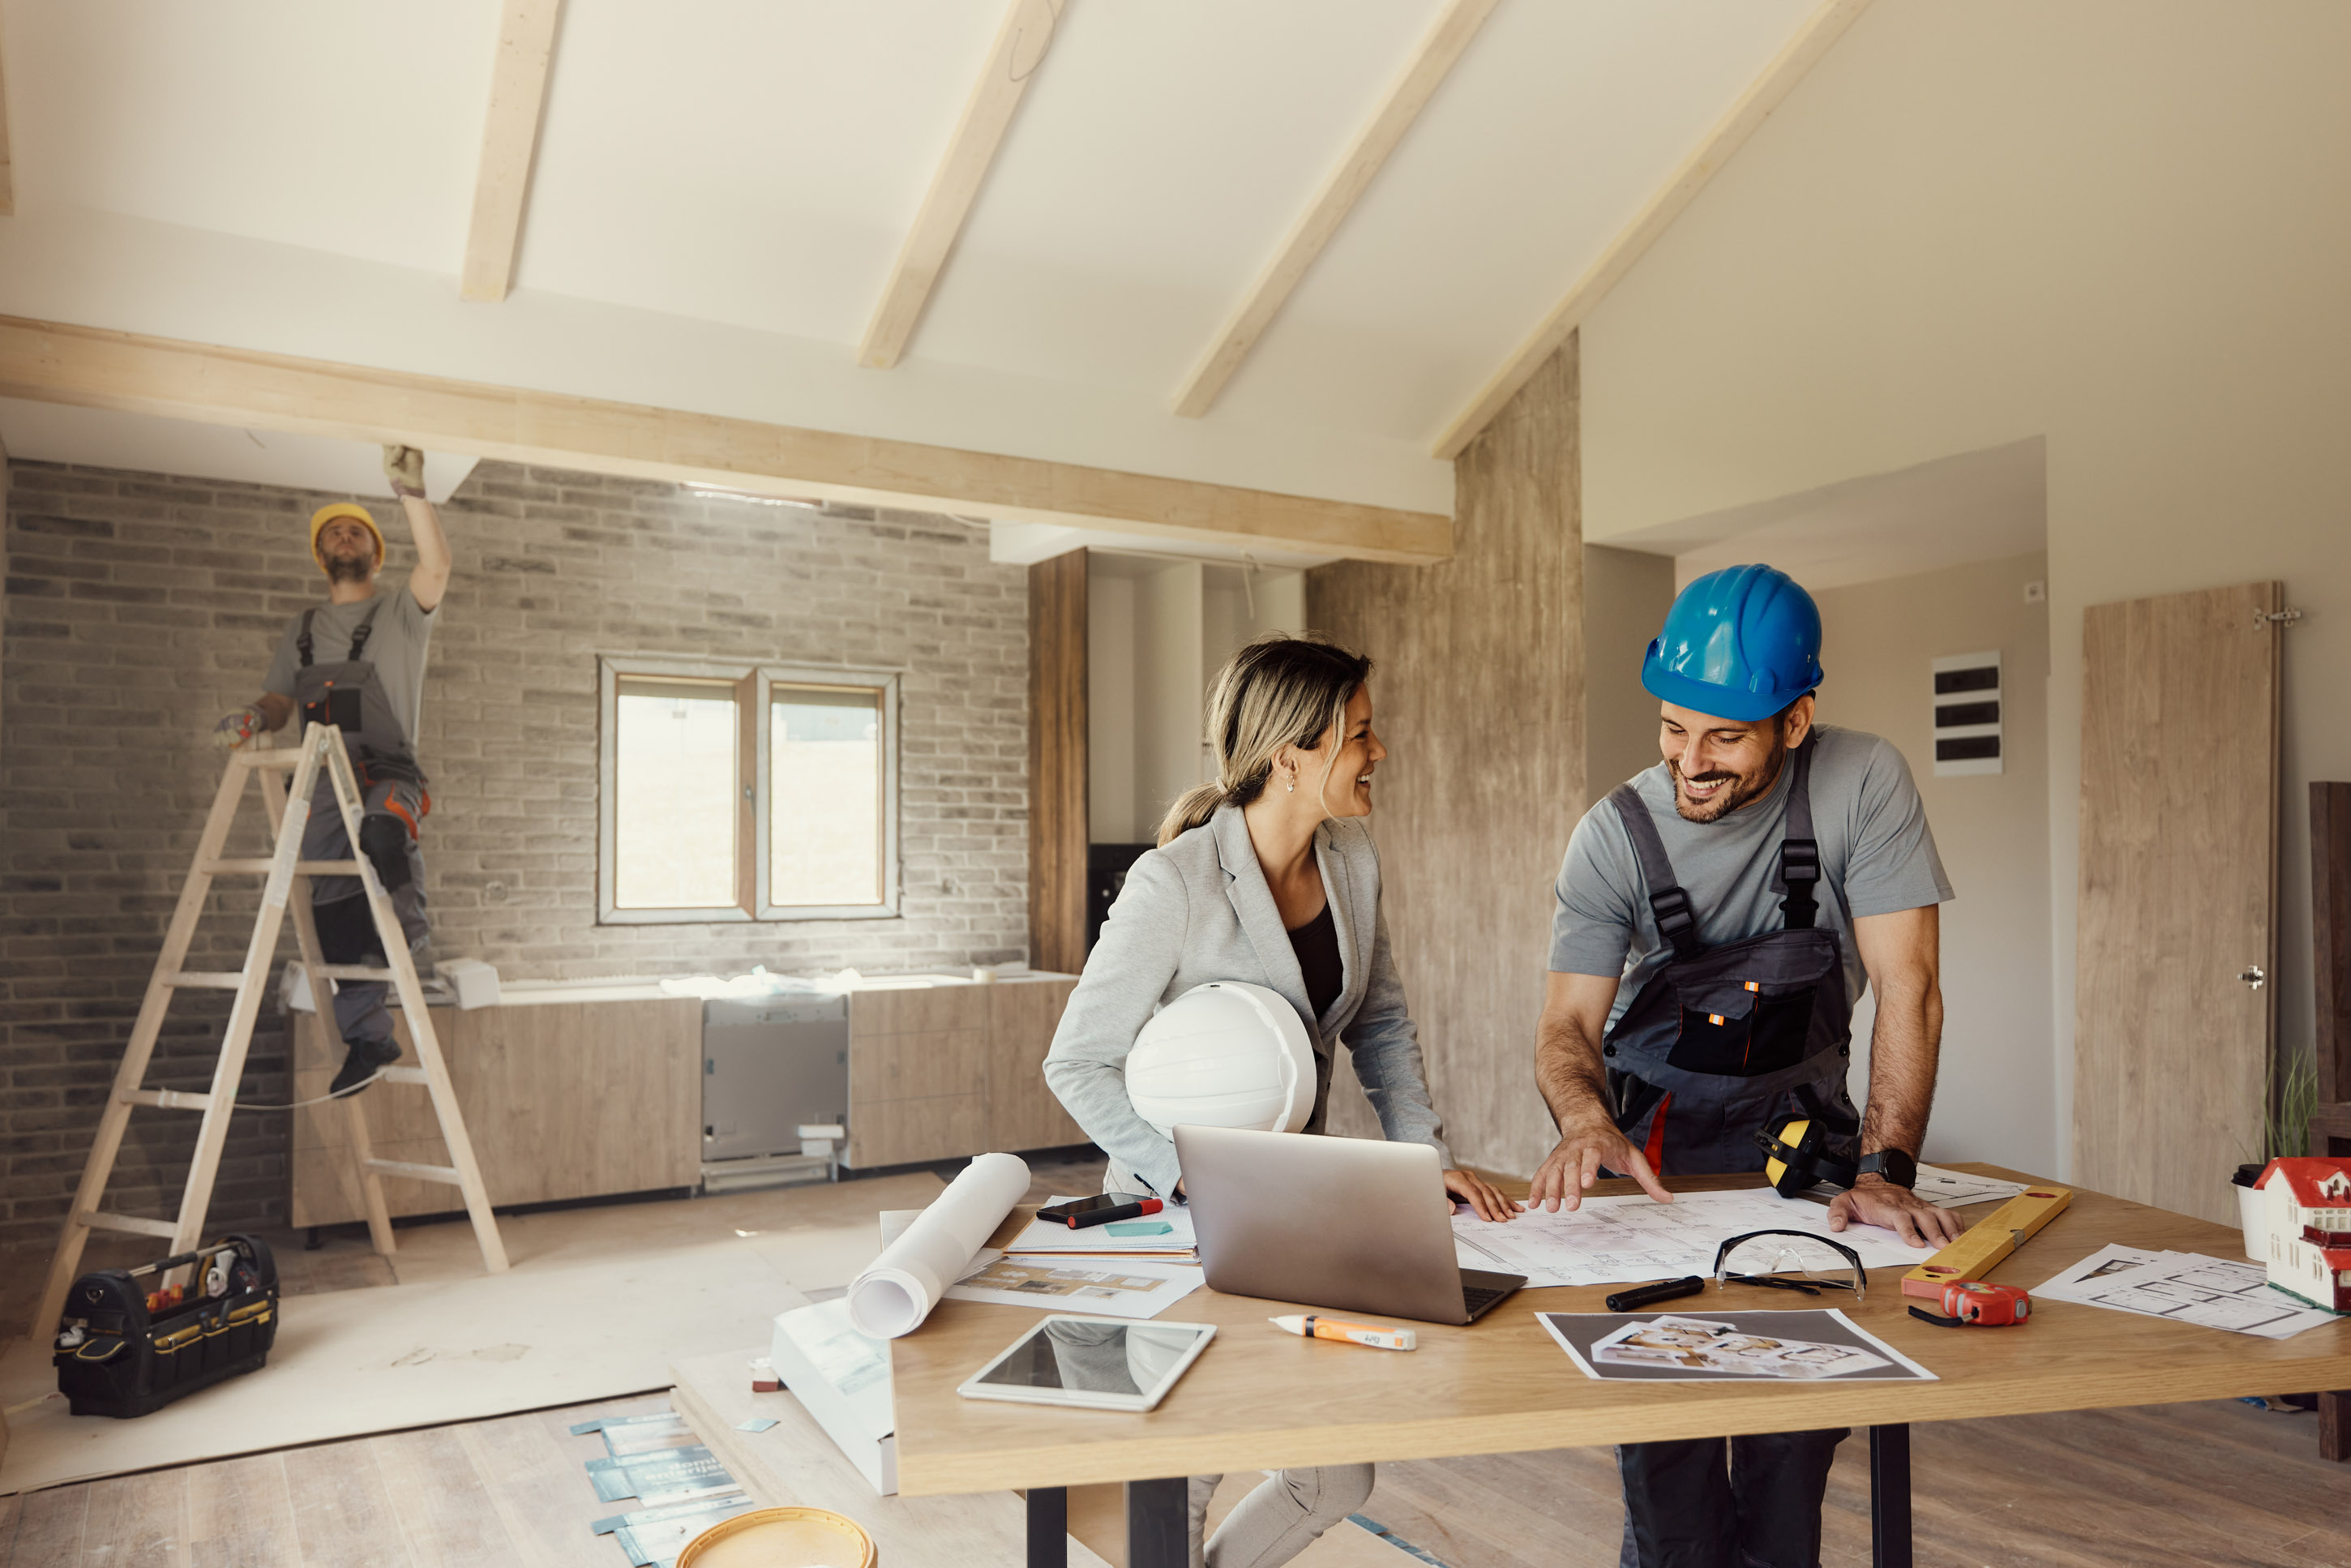
A Genuinely Good Change: Immediate Expensing Is Back
For years, a rule under Section 174 forced firms to capitalize and amortize domestic research costs over five years rather than deducting them immediately — a change that quietly increased tax bills for firms doing qualifying R&D work, sometimes dramatically. Recent legislation restored the ability to fully and immediately deduct domestic research expenses starting in 2025, which is a meaningfully better outcome for firms doing genuine R&D-qualifying design work. Foreign research costs still have to be amortized over 15 years, so where your design and engineering work actually happens matters more than it used to.
| Research Location | Current Treatment |
|---|---|
| Domestic (U.S.-based) research | Immediately deductible in the year incurred |
| Foreign research | Amortized over 15 years |
A Real Window for Small Firms to Go Back and Claim This
If your firm's average annual gross receipts are under roughly $31 million, you may be eligible to amend returns from 2022 and 2023 to fully expense research costs that were previously forced into the slower amortization schedule, along with updating related elections. This lookback window is time-limited, with the relevant amendment deadline running through mid-2026 — meaning firms that qualify and haven't acted yet are working against a real, approaching cutoff, not an open-ended opportunity.
The 179D Deduction: A Genuinely Architecture-Specific Incentive
Separate from the R&D credit, Section 179D offers a deduction for designing energy-efficient commercial buildings. What makes this particularly relevant for architecture firms: for projects involving tax-exempt entities — public schools, government buildings, nonprofit-owned facilities, religious institutions — the building owner often can't use the deduction themselves, since they don't pay federal income tax. In these cases, the deduction can be allocated to the person primarily responsible for the building's design, meaning your firm, not the building's owner, may be able to claim it directly.
What Actually Supports a Claim
Recent updates to the relevant IRS form now require firms to clearly explain what was developed, why the work qualifies as genuine research, and what it cost — at the level of individual projects or business components, not just a lump total. Firms that tag time entries to specific projects, document the technical uncertainty being resolved, and keep this contemporaneously rather than reconstructing it later are in a far stronger position if a claim is ever reviewed.
How We Help Maryland Engineers & Architects
At Mercer Flanagan, we work with engineers and architects throughout Frederick County and central Maryland to evaluate whether your design work qualifies for the R&D credit, assess whether the small business lookback window applies to your firm, and explore 179D opportunities on projects involving tax-exempt building owners.
- Tax planning around R&D credit eligibility and project documentation
- Bookkeeping and accounting with project-level cost tracking that supports a credit claim
- Business tax preparation for engineering and architecture firms of all sizes
Book a free consultation and we'll walk through your specific situation — no pressure, no obligation.
Frequently asked questions
No. If your staff uses engineering or design expertise to resolve genuine technical uncertainty on a project, that work may qualify even without a formally separate research department.