Real Estate Investing
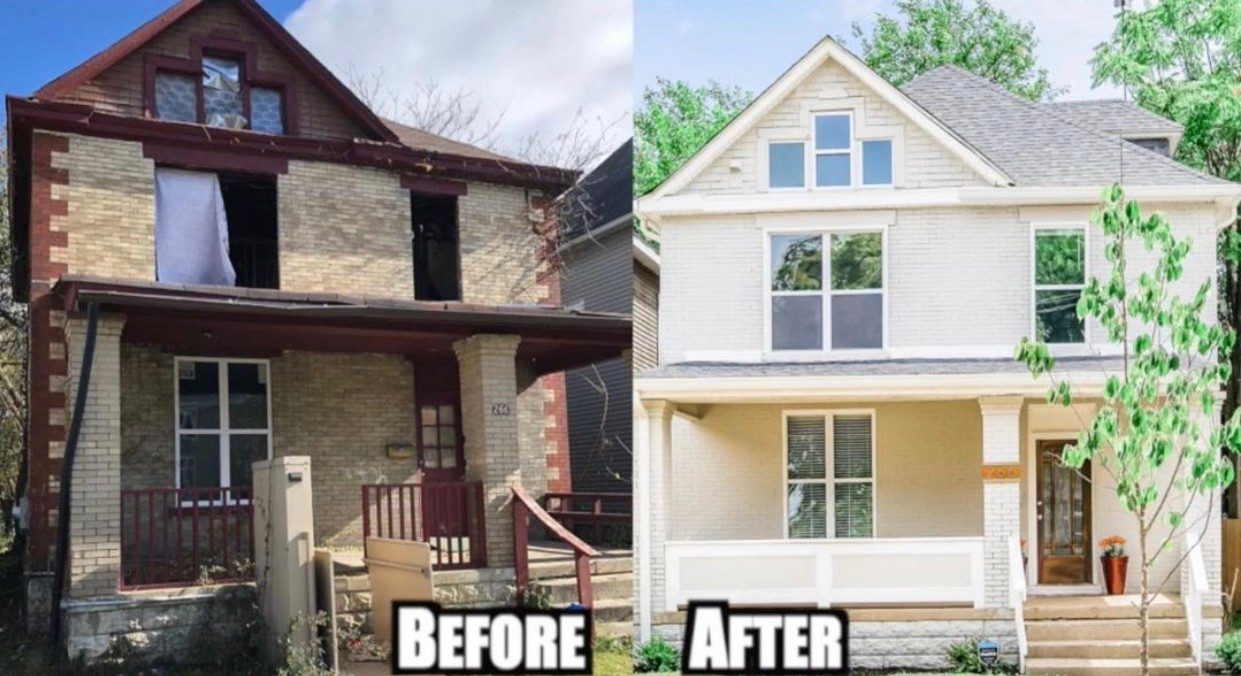
Many new flippers assume that holding a property for a year, or rolling profits into the next deal, will get them favorable capital gains treatment. For most active flippers, neither one works the way they expect.
If you're flipping houses anywhere in Frederick County or central Maryland, the single most important tax question isn't "how do I save on this flip" — it's "how is the IRS going to classify what I'm doing in the first place." That classification decides almost everything else.
Dealer vs. Investor: There's No Bright-Line Test
The tax code draws a sharp distinction between a real estate "dealer" and a real estate "investor," and the consequences of landing on the wrong side of that line are significant. A dealer is treated as holding inventory — properties bought with the primary intent to resell, much like a retailer holding merchandise on a shelf. An investor is treated as holding a capital asset — property held for appreciation or rental income.
Here's the part that surprises most new flippers: there's no single rule, like a one-year holding period, that automatically makes you an investor. The IRS and courts look at the full picture — how frequently you buy and sell, how the property was advertised, the extent of improvements made, your stated intent at purchase, and the overall pattern of your activity. If you're actively flipping multiple properties a year, you're very likely a dealer regardless of how long you happen to hold any single one.
Why This Classification Costs So Much
Dealer profits are taxed as ordinary income — up to 37% at the federal level — and on top of that, self-employment tax adds another 15.3% on the first $184,500 of net earnings for 2026, with 2.9% continuing above that. An investor's profit, by contrast, may qualify for long-term capital gains rates of 0%, 15%, or 20% if the property was genuinely held for investment, with no self-employment tax at all.
| Classification | $50,000 Profit Example | Approximate Tax |
|---|---|---|
| Investor (Long-Term Capital Gains) | Held for genuine investment, sold after 1+ year | Roughly $7,500–$10,000 |
| Dealer (Ordinary Income + SE Tax) | Active flip, regardless of holding period | Roughly $16,000–$26,000 |
That gap, repeated across multiple flips a year, is the difference between a profitable side business and one that's quietly losing far more to tax than necessary.
Why 1031 Exchanges Don't Work for Flips
A 1031 exchange lets an investor defer capital gains tax by rolling proceeds from one investment property into another like-kind property. It's a genuinely valuable tool — for investors. The exchange is explicitly limited to property held for investment or for productive use in a trade or business, and flip inventory held primarily for resale is specifically excluded.
I can roll a flip's profit into the next one with a 1031 exchange.
1031 exchanges don't work for flips.
Attempting to run a flip through a 1031 exchange is one of the most consequential mistakes a flipper can make. If the IRS determines the property was dealer inventory, the entire exchange can be disallowed, triggering immediate tax on the full gain plus penalties — often a worse outcome than if the exchange had never been attempted at all.
The Cash Flow Trap: When Rehab Costs Actually Become Deductible
Many new flippers assume renovation costs — materials, labor, permits — are deductible as they're paid. They're not. These costs are generally capitalized into the property's basis and only become deductible when the property actually sells, as part of the cost of goods sold calculation.
This creates a real cash flow mismatch: you're paying contractors and suppliers throughout the renovation, but you don't get the corresponding tax benefit until the sale closes, sometimes months later. Flippers who don't plan for this timing gap can end up surprised by how little their renovation spending actually reduces their tax bill in the year they spent the money.
The S-Corp Strategy: Reducing the Self-Employment Tax Bite
Since dealer status forecloses capital gains treatment regardless of structure, the realistic planning opportunity for most active flippers is reducing the self-employment tax portion rather than escaping ordinary income tax entirely. Operating through an S-Corp lets you split your profit into a reasonable W-2 salary, which is subject to self-employment tax, and a remaining distribution, which is not.
For a flipper netting $200,000 a year, paying a reasonable salary of roughly $80,000 to $100,000 and taking the rest as a distribution can save somewhere in the range of $15,000 to $17,000 annually in self-employment tax — without changing the underlying ordinary income tax rate on the profit itself.
One Exception Worth Knowing: The Live-In Flip
If you genuinely move into a flip and live there as your primary residence for at least two of the five years before selling, you may qualify for the Section 121 home sale exclusion — up to $250,000 of gain excluded for single filers, $500,000 for married couples filing jointly. This is a real, legitimate strategy for flippers willing to live in a property during a longer renovation, though it obviously doesn't work for a rapid-turnover flipping model.
How We Help Maryland House Flippers & Investors
At Mercer Flanagan, we work with house flippers and real estate investors throughout Frederick County and central Maryland to structure flipping activity correctly from the start, keep flip and rental activity properly separated, and minimize self-employment tax through entity structure rather than wishful 1031 thinking.
- Bookkeeping and accounting that tracks renovation costs and basis correctly per project
- Tax planning around quarterly estimated payments and S-Corp election timing
- Individual and business tax preparation for sole proprietors, S-Corps, and multi-entity flipping operations
Book a free consultation and we'll walk through your specific situation — no pressure, no obligation.
Frequently asked questions
Not by itself. Holding period alone doesn't determine dealer versus investor status. If your intent was to fix up and resell the property, the IRS and courts can still classify you as a dealer regardless of how long you held it.